
SoLo Funds: Lend & Borrow
- Rating
- 4.6
- Downloads
- 500.00K
- Content Rating
- Everyone
SoLo Funds: Lend & Borrow - Screenshots
Pros
- Quick access to peer-to-peer borrowing without traditional bank applications.
- Borrowers can build a visible repayment history within the community.
- Loan requests and repayment terms are presented in a straightforward format.
- The app supports direct communication between borrowers and lenders.
- Useful option for users with limited access to conventional credit products.
Cons
- Availability and features may vary depending on your location and eligibility.
- Late repayments can affect your standing and future access to funds.
- Borrowing costs and optional tips may be difficult to compare at a glance.
- Peer funding is not guaranteed
- so requests may remain unfulfilled.
- Identity verification and financial information are required to use core features.
SoLo Funds: Lend & Borrow - Description
- App Name
- SoLo Funds: Lend & Borrow
- Package Name
- com.solofunds
- Developer
- Solo Funds
- Category
- Finance
- Last Updated
- Oct 22, 2021
- Version
- 2.19.0
When an unexpected bill lands before payday, most people want a short bridge rather than a long-term loan. That is the situation I kept in mind while reviewing SoLo Funds: Lend & Borrow, a finance app from Solo Funds built around borrowing and lending between members. Its central idea is simple: a borrower requests money on their own terms, while another member can choose whether to provide it and potentially benefit from doing so.
I like that the app approaches a cash shortage differently from a conventional bank product. It is not presented as a general budgeting suite, an investing dashboard, or a traditional credit card. The experience is focused on connecting people who need a relatively short-term financial handoff with people willing to fund that request. That focus makes the app easy to understand, but it also means the quality of the experience depends heavily on timing, available participation, and the user's ability to manage repayment responsibly.
SoLo Funds is free to install and is listed for Everyone, which makes it approachable for a broad audience. It has reached over 500 thousand installs and carries a 4.6 average from around 25 thousand ratings, with roughly 5.6 thousand written reviews. Those figures suggest that many users find the basic concept useful, although they should not be treated as a promise that every request will be funded or every borrowing experience will feel effortless.
From a cash shortfall to a completed handoff
Starting with the problem rather than the product
The most useful way to understand this app is to begin outside the app. Imagine that my car needs an urgent repair, my utility payment is due, or a necessary purchase arrives a few days before my regular income. I know when I expect to have money again, but I do not want to turn a temporary gap into a large, long-running balance. In that situation, a peer-to-peer borrowing platform may feel more relevant than applying for a conventional loan.
That does not mean I would open it for every financial inconvenience. I would first ask whether the expense is genuinely necessary, whether repayment fits my next income cycle, and whether using the service could create a second problem. A short-term advance only helps when the future repayment is realistic. If my income is already committed to rent, food, transport, and other essentials, adding a repayment obligation is not a solution simply because the request can be made from a phone.
This is one of the app's most important practical lessons: the request should begin with a repayment plan, not just an urgent need. Before entering anything, I would write down the amount required, the date I expect to repay it, and the bills that will arrive before then. That small preparation makes the app more useful because it turns an emotional moment into a decision with boundaries.
Setting up a borrowing request
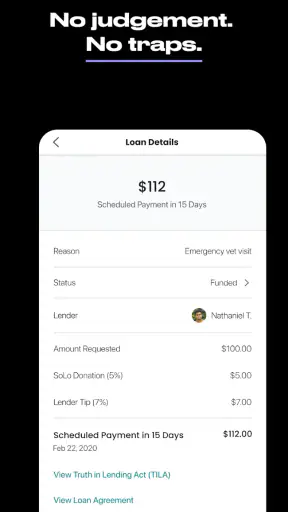
The borrowing side is designed to guide the user toward presenting a request to other members. I found the social structure significant because the request is not merely an invisible application sent into a bank's automated system. It is an appeal that another person may decide to support. That changes how I would describe the need: clearly, briefly, and honestly, without asking for more than the actual shortfall.
A realistic workflow would be to open the app, review the borrowing options available to me, enter a carefully calculated amount, and select terms that match the date my money should arrive. I would check every field before submitting because a mistake in the requested amount or repayment timing can affect both sides of the transaction. The app's value is not in making a user rush; it is in giving that user a structured place to organize the request.
One non-obvious advantage of this approach is that it encourages a separation between the need and the amount. When people are stressed, they often round up or borrow a little extra for comfort. I would resist that temptation here. Asking only for the bill, repair, or purchase that caused the gap keeps the eventual repayment smaller and makes the request easier to justify to myself and to potential lenders.
At this point, I would also make sure that my account and payment details are accurate. Financial apps are less forgiving than ordinary social apps when a handoff depends on correct identity and payment information. Even without adding unnecessary personal details, I would take time to read each screen, confirm the destination of funds, and understand what action the app expects next.
What happens while the request waits
After a request is submitted, the experience changes from preparation to waiting. This is where SoLo Funds differs most from a standard overdraft or a credit product that makes a decision through a fixed approval process. Another member has to choose whether the request fits their willingness to lend. The result may therefore depend on the strength of the request, the timing, and the participation available when I submit it.
I would not treat a submitted request as money already in my account. That distinction matters in an emergency. If a bill must be paid immediately, I would keep a backup plan rather than assuming that a peer-funded request will complete in time. The app can be useful for bridging a gap, but it should not be the only plan for a deadline that cannot move.
For borrowers, the handoff has a human element that can be both reassuring and uncomfortable. It may feel more personal than dealing with a faceless lender, but that also means the responsibility is visible in a different way. I would use plain language and avoid promising a repayment date based on hope. If my income schedule is uncertain, I would consider whether borrowing is appropriate at all.
A helpful habit is to prepare the repayment money before it is technically due. If I expect my paycheck on Friday, I would treat the repayment as the first destination for that money rather than waiting until the deadline arrives. This is a stronger workflow than borrowing now and deciding later how to fit the obligation into the rest of the month.
The lender's side of the same journey
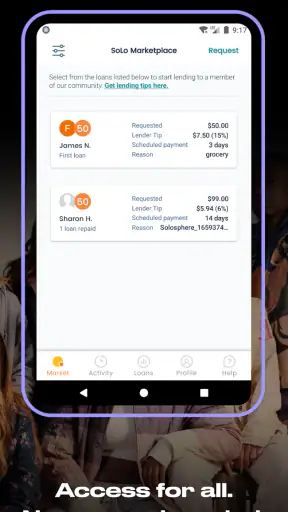
The lending flow gives the app a second audience. A member with available money can review opportunities to lend and decide whether a particular request suits their own risk tolerance and cash needs. The appeal is clear: instead of leaving spare funds idle, a lender may choose to help another member and potentially receive a benefit from doing so.
In my view, the most important lender insight is that this is not the same as a savings account. Money committed to someone else's request should be treated as money that may not be available for my own emergency. I would never lend rent money, a tax payment, or the cash I need for a near-term obligation just because a request looks sympathetic. The social purpose of the platform does not remove the financial risk of parting with funds.
I would also avoid judging a request only by its story. A compelling explanation can help me understand the situation, but I would still consider the amount, the proposed timing, and whether I can accept the possibility of delay. The strongest lender workflow is deliberately unemotional: review the request, decide on a small amount I can afford to set aside, and stop when that limit is reached.
This creates a meaningful trade-off. Borrowers may appreciate access that feels more personal than a traditional lender, while lenders gain a direct way to support individuals. At the same time, both sides must tolerate more uncertainty than they might with a conventional financial product. That uncertainty is not a flaw I would ignore; it is part of what makes the model different.
Handoffs, notifications, and responsibility
The most delicate part of the experience is the movement of responsibility from one person to another. A borrower submits a request, a lender decides to participate, and the app facilitates the connection between those intentions. Each handoff can introduce friction: the request may take time, the amount may not fit what a lender wants to provide, or the timing may no longer match the original need.
I would keep notifications enabled for the app if I were actively using it, not because every alert needs an immediate response, but because financial handoffs are easier to manage when I know what stage they have reached. I would still open the relevant screen and verify the details rather than relying on a notification preview. That extra check is especially worthwhile when money is moving or a repayment action is approaching.
For a borrower, the practical question is not only “Can I request money?” but also “What do I do if the request is not completed quickly enough?” My answer would be to decide that before submitting: contact the bill provider, use an existing emergency reserve, postpone a nonessential purchase, or ask a trusted person directly. Having that fallback prevents the app from becoming a source of false confidence.
For a lender, the equivalent question is “Can I afford to wait for this money?” If the answer is no, I would not participate. That rule is simple but easy to overlook when the lending opportunity appears attractive. The app's social design may encourage generosity, yet a lender still needs a personal boundary that comes before the requester's urgency.
Reaching the result
The successful outcome is straightforward: the borrower receives help with a temporary gap, and the lender has supported the request under the agreed arrangement. In the best case, the user gets through the immediate expense without turning it into a larger financial burden. That is where I see the strongest use case for SoLo Funds: a disciplined, short bridge for someone who knows exactly when and how the obligation can be handled.
I would record the repayment date outside the app as well. A calendar reminder, a note in my budget, or an automatic transfer plan can make the commitment harder to forget. This is a concrete workflow improvement because the app should not be expected to carry my entire financial memory. The more important the payment, the less I would rely on a single notification or a quick glance at an account screen.
After the borrowing cycle ends, I would review what caused the shortfall. If it was a one-time repair, the service may have done exactly what I needed. If the same gap appears every month, repeated borrowing points to a structural budget problem. In that case, a spending review, income adjustment, or longer-term financial counseling would be more appropriate than using the app repeatedly as a substitute for missing cash flow.
Lenders should perform a similar review. If the experience leaves them uncomfortable with the amount of money tied up or the uncertainty involved, they should reduce future participation or stop lending. The potential benefit is not worth ignoring personal liquidity. A good result is not only a completed transaction; it is a transaction that leaves both sides financially stable enough to handle their next obligation.
Where the flow breaks down
The first breaking point is urgency. If I need guaranteed funds at a precise moment, a peer-to-peer request may not be the best fit because another member must decide to participate. A bank account buffer, an established credit line, or direct help from someone I trust may be more predictable, even if those alternatives have their own costs or limitations.
The second is repayment uncertainty. Someone whose income date changes frequently, whose essential expenses already exceed their available money, or who is using one advance to cover another should be cautious. The app may make the request process feel manageable, but it cannot make an unaffordable repayment affordable. I would skip it when the only proposed repayment plan is “I will figure it out later.”
There is also friction in explaining a request to strangers. Some people will prefer the privacy and predictability of a conventional financial provider. Others may find the lending model appealing but dislike the emotional pressure of knowing that another individual is connected to their financial situation. Neither reaction is unreasonable. The right choice depends on whether the social handoff feels like a useful alternative or an added burden.
Lenders face a different failure point: availability. Money placed into a lending opportunity is not money I can necessarily use for an unexpected expense. I would therefore keep a separate emergency reserve and set a strict maximum for lending. If I could not comfortably lose access to the funds for a while, I would choose not to lend, regardless of how persuasive the request seemed.
Privacy and security also deserve attention. I would use a strong device passcode, avoid entering financial information on an unsecured network, and review the app's screens carefully before confirming a transaction. These are not reasons to reject the service specifically; they are sensible precautions whenever an app handles borrowing, lending, identity, or payment details.
Who should use it, and who should look elsewhere
I think SoLo Funds is best suited to a borrower facing a defined, short-lived cash gap with a dependable repayment event ahead. It may also suit a lender who understands that participation is not the same as keeping cash in a conventional deposit account and who is comfortable setting aside only money they can afford not to need immediately.
I would point a friend toward it when they can name the expense, calculate the exact amount, and explain how the repayment fits into their next budget. I would not recommend it as a routine way to cover groceries, recurring bills, or an income shortfall that has no clear end. In those cases, the app may mask the underlying issue while adding another date to remember.
Compared with a bank loan, the app's peer-to-peer structure can feel more direct and tailored, but it may offer less certainty about timing. Compared with an overdraft, it may encourage a more deliberate request rather than allowing spending to continue automatically, yet it still creates an obligation that must be respected. Compared with asking family or friends, it provides a formal digital setting, though it does not remove the need for trust and responsibility between people.
The app is free, and its Everyone age rating makes the initial barrier low, but free access should not be confused with cost-free borrowing or risk-free lending. I would read the terms shown during the actual transaction and make sure I understand the financial consequences before confirming anything. That is especially important because a user's circumstances matter more than the simplicity of the interface.
My conclusion after following the full workflow
Solo Funds has a clear identity as a finance app for arranging short-term borrowing and voluntary lending between members. I appreciate the way it gives both sides an active role: borrowers can frame a request around a real need, while lenders can choose whether helping fits their own finances. The concept feels more human than an automated credit decision, and that can be valuable when a temporary problem does not fit neatly into a traditional product.
My recommendation comes with firm conditions. Borrowers should enter with a precise amount, a credible repayment date, and a backup plan in case the handoff takes longer than expected. Lenders should use only genuinely spare money and should treat the arrangement as something that can affect their liquidity. If either side ignores those boundaries, the app's convenience can become a source of pressure.
The current release is version 2.19.0, and the app supports Android 8.0 or later. For someone whose financial situation matches its intended workflow, it is worth considering as a focused alternative to more familiar borrowing routes. For anyone seeking guaranteed instant cash, long-term debt management, or a complete budgeting system, I would choose a different tool. Used carefully, though, SoLo Funds can turn a temporary cash-flow problem into a structured handoff rather than an improvised financial decision.
FAQ
What is SoLo Funds: Lend & Borrow?
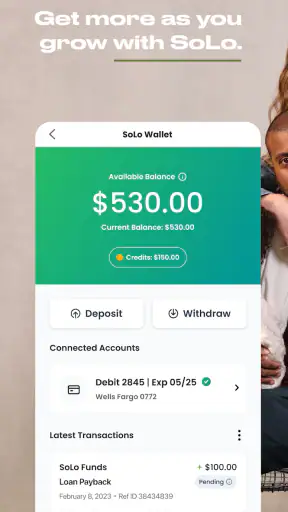
SoLo Funds is a community-based financial platform designed to help members request small, short-term advances from other users instead of relying on traditional payday loans or overdraft services. Borrowers can request money for urgent expenses, while lenders may contribute funds and receive optional tips. Availability, eligibility, fees, and specific features can vary depending on your location and account status.
How does borrowing money through SoLo Funds work?
After creating an account and completing the required verification, eligible users can submit a request describing how much they need and when they plan to repay it. Other community members may choose to fund the request. Once funded, the money is transferred according to the app’s process, and repayment is scheduled for the selected date. Always review the total amount due and all terms before accepting.
Can I make money by lending through SoLo Funds?
SoLo Funds allows eligible members to provide money to borrowers, and lenders may receive a voluntary tip when a loan is repaid. However, lending is not guaranteed to produce a profit, and repayment may be delayed or incomplete depending on the borrower and the platform’s policies. Users should understand the risks, protection limits, and applicable terms before committing funds.
Are there fees or interest charges on SoLo Funds?
The cost of using SoLo Funds can depend on the transaction, account type, repayment behavior, and current platform policies. The service is generally structured around optional tips and possible fees rather than conventional interest, but users may still encounter charges for certain features or situations. Carefully check the final repayment amount, due date, and fee disclosures in the app before confirming.
Is SoLo Funds safe and available to everyone?
SoLo Funds uses account verification and payment-security measures, but no financial platform is completely free from risks such as fraud, missed repayments, account issues, or unauthorized access. Eligibility may depend on age, location, identity verification, banking details, and other requirements. Before downloading, confirm that the app operates in your region, read its privacy and user agreements, and use strong account-security practices.


